Fortescue's CMRG negotiations matter after the ore leaves Australia
September sales were 3.9Mt below shipments. The full quarterly report makes product placement and conditional guidance central to the iron-ore case.
 Global Mining & Metals · OCTOBER 29, 2026
Iron ore, met coal and steel — the dirty backbone the clean economy is bolted to.
Model demonstration: news, volume and equity inputs are illustrative.
| Iron Ore (62% Fe) US$/t · Illustrative sample · 2026-06-16 | 102 | -10.0% 6M | -14.0% 1Y | 39 | |
| Coking Coal (premium HCC) US$/t · Illustrative sample · 2026-06-16 | 188 | -12.0% 6M | -18.0% 1Y | 40 | |
| Steel (HRC, US) US$/short ton · Illustrative sample · 2026-06-16 | 760 | -4.0% 6M | -8.0% 1Y | 45 |
What the spot price won't tell you: the shape of the futures curve (who's paying up for metal now) and where warehouse stock is heading. Figures are indicative until a live LME/CME feed is wired.
Illustrative example — not current exchange quotes. This curve does not update automatically.
Spot trades over deferreds — the market is paying up for metal now. Tight physical, bullish tell.
Sample data for explaining term structure.
September sales were 3.9Mt below shipments. The full quarterly report makes product placement and conditional guidance central to the iron-ore case.
Onslow's operating progress is real, but September had little cash interest and October starts to reflect higher diesel prices. The quarterly timing matters.
worldsteel's October outlook gives India a substantial role in forecast steel-demand growth. Converting that into an Australian iron ore or coal thesis requires more than comparing percentage growth rates.
Rio’s third-quarter update puts Simandou at an annualised production rate of about 10 million tonnes. Its reporting notes explain why mine output, sales and shareholder cash need separate treatment.
Macarthur Minerals received an additional Programme of Work approval from WA's DMPE for proposed hematite and magnetite bulk sampling in the Central region of its 100%-owned Lake Giles Hematite Project, complementing an April 2026 PoW.
Queensland's top coal royalty rate is 40 per cent — nearly four times the Queensland Resources Council's cited global average of 12.9 per cent, and above New South Wales (10.8 per cent), the current US federal coal royalty (7 per cent), and British Columbia's net-revenue tax (2–13 per cent, and only after capital is recovered). QRC is a lobby group with an obvious stake in that comparison, but the design flaw underneath it — a price-tier royalty with no reference to cost — is real regardless of who's pointing at it.
The Nightly reported on 28 August 2026 that BHP is cutting roles at Mining Area C as autonomous haulage expands into MAC East. Industry sources, not the company, floated ‘up to about 10 per cent’ of a 1,596 headcount; BHP has not confirmed a number.
On 26 August 2026 the WA government and the Yindjibarndi Ngurra Aboriginal Corporation both appealed the May Federal Court native-title compensation award against Fortescue. The cultural figure is reported as A$150 million; the economic-loss line is not.
Mineral Resources (ASX:MIN) shares have roughly quadrupled from their 2025 low since the board announced in November 2024 that founder Chris Ellison would step down within 18 months — but the exit that supposedly justified the sell-off, and the recovery, never actually happened.
Champion Iron expects first commercial DR-grade pellet feed from its Bloom Lake DRPF project by the end of June 2026, upgrading roughly half of the mine's output toward 69% Fe just as steel decarbonisation lifts demand for low-impurity ore.
Three Bowen Basin coking-coal names — Vitrinite, Bowen Coking Coal and Fitzroy — have all hit the wall or changed hands in under a year, and the common thread is the price of money, not the price of coal.
Queensland's 2022 progressive coal royalty, topping out at a 40% marginal rate, is now reshaping investment and production decisions across the Bowen Basin's coking-coal producers.
The least glamorous tonne in mining bankrolls the most glamorous bets. Before you get excited about a copper growth pipeline, ask where the cash to build it comes from. The answer is usually red dirt from the Pilbara.
| Operation | Country | Owner | Stage |
|---|---|---|---|
| Lake Giles | Australia | Macarthur Minerals | Development |
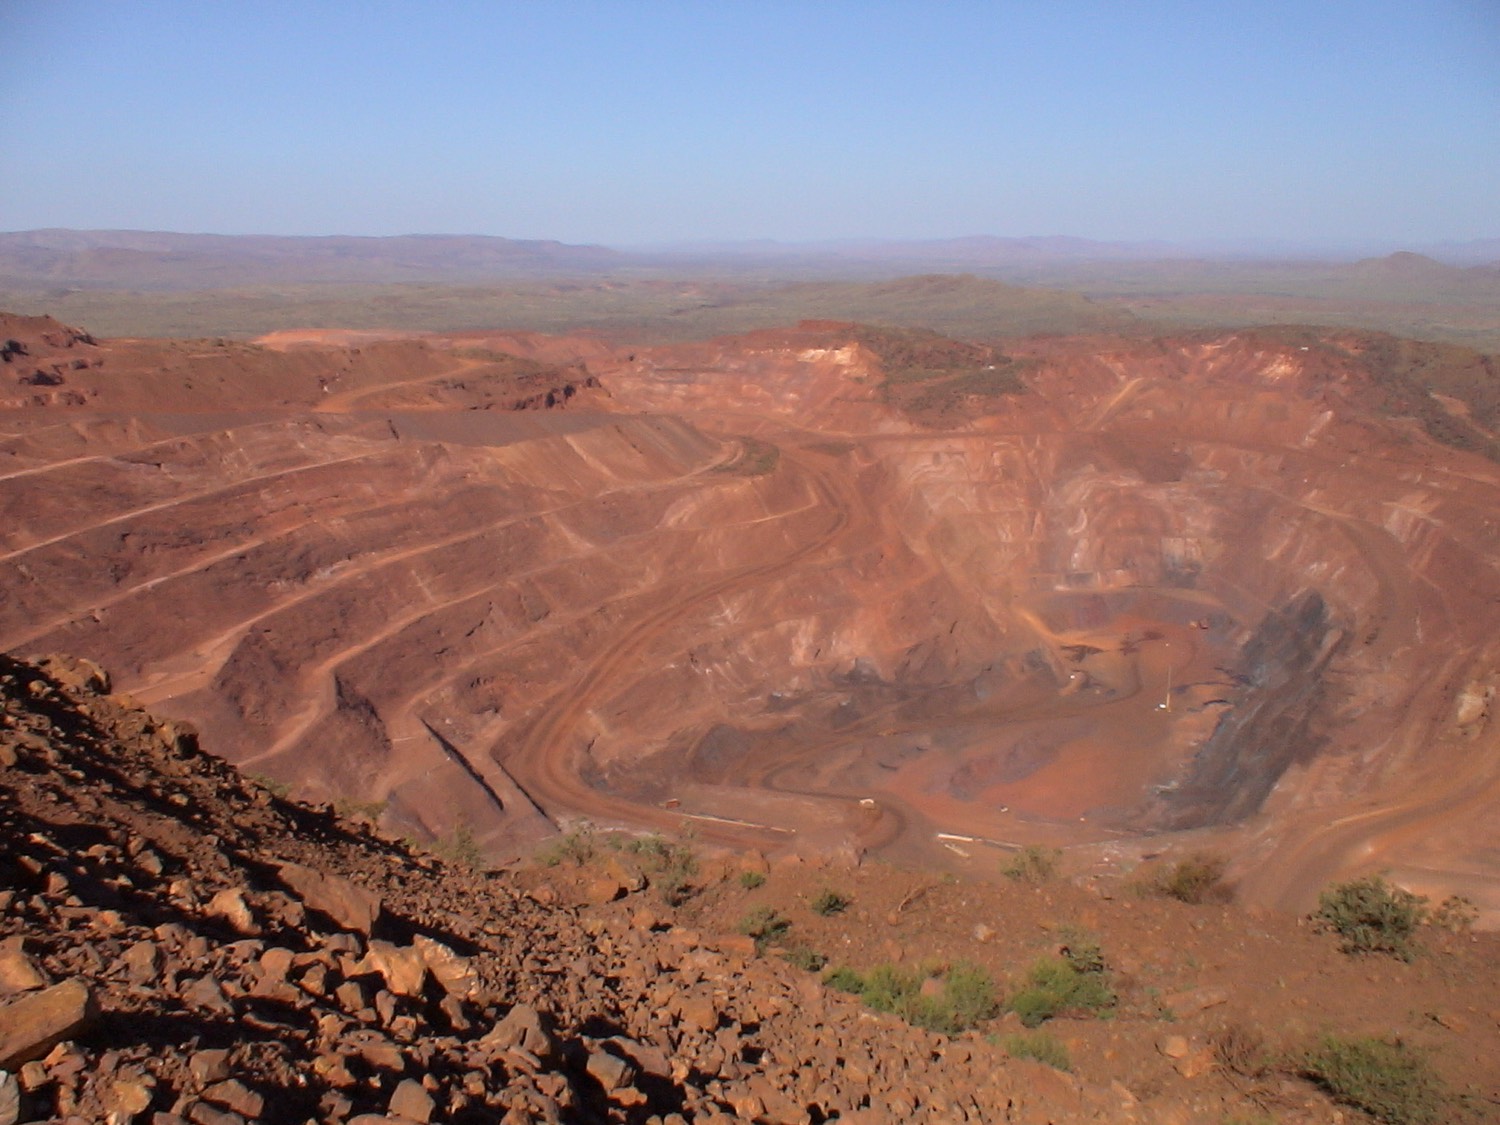
| Pilbara (iron ore hubs) | Australia | BHP, Rio Tinto, Fortescue | Producing |
| Onslow Iron | Australia | Mineral Resources | Producing |
| Vulcan Complex | Australia | Vitrinite (in receivership — KordaMentha / Cor Cordis) | Care & Maintenance |
| Bowen Basin | Australia | BHP/Mitsubishi (BMA), Glencore, others | Producing |
| Carajás | Brazil | Vale | Producing |